👋 Welcome to Paul Hanson Agency — State Farm Insurance in Sauk Rapids, MN
Since 1984, our team has helped families and businesses across Sauk Rapids, Sartell, St. Cloud, Foley, and the surrounding Benton, Stearns, Morrison, and Sherburne County communities protect what matters most — auto, home, renters, life, and business coverage, plus an annual review we call The Simple Conversation. Guidance that's personal, practical, and straightforward.
🍂 October in Sauk Rapids brings harvest traffic, earlier sunsets, active deer and the first reminders that winter is close.
For drivers on Highway 10 and rural roads around Sauk Rapids, October is a good time to ask how comprehensive and collision coverage may respond differently to a deer strike, a slide into a ditch or impact with another object. Colder nights and the start of heating season also make it practical to review how home or renters coverage may respond to fire, smoke, frozen or burst pipes, water backup and additional living expenses if a covered loss makes the property unlivable.
🚗 Auto: Review comprehensive and collision selections, deductibles and roadside assistance before fall travel around deer and slow-moving farm equipment.
🏠 Home: Test smoke and carbon monoxide alarms, service heating equipment and ask whether water-backup protection is included or needs to be added separately.
🔑 Renters: Confirm how your belongings and additional living expenses may be handled after a covered fire, smoke or water loss.
The Sauk Rapids Fire Department Annual Open House is Saturday, October 10, from 10 a.m. to 1 p.m. at 408 N Benton Drive. Families can see the fire trucks and an extrication demonstration, while children can spray water hoses and pick up pumpkins and fire-safety materials during Fire Prevention Week.
Before the leaves are gone and the snow starts to fly, call or stop in for The Simple Conversation so we can walk through your coverage in plain language.
About Paul
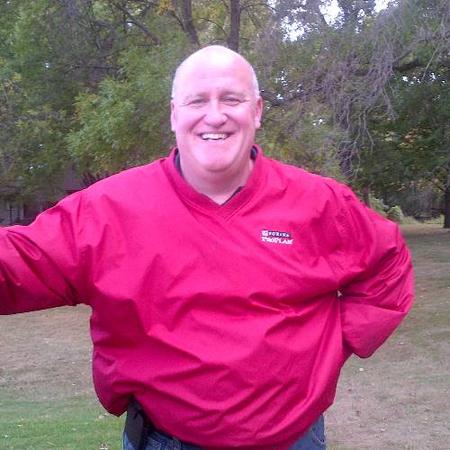
I'm Paul Hanson — a second-generation State Farm agent serving Sauk Rapids and Central Minnesota since 1984. My family has been helping people protect what matters most since 1969, and that same purpose drives everything we do today.
A little more about me:
👨👧👦 Proud dad of five and owner of four Labrador Retrievers
🏈 Former youth sports coach in football, hockey, and baseball, now proudly cheering on my son's baseball team as one of its biggest fans
🌿 Volunteer and former National Chairman of Pheasants Forever
🏆 Sartell Citizen of the Year, 2014 — co-creator of Pinecone Park, a 12-field youth sports complex serving families across Central Minnesota
🤝 St. Cloud Area Chamber of Commerce member since 2000
🔨 Central Minnesota Builders Association member since 2000
Being part of this community is not something I take lightly. I look forward to helping you and your family navigate life's changes with the coverage and confidence you deserve.
Our Team
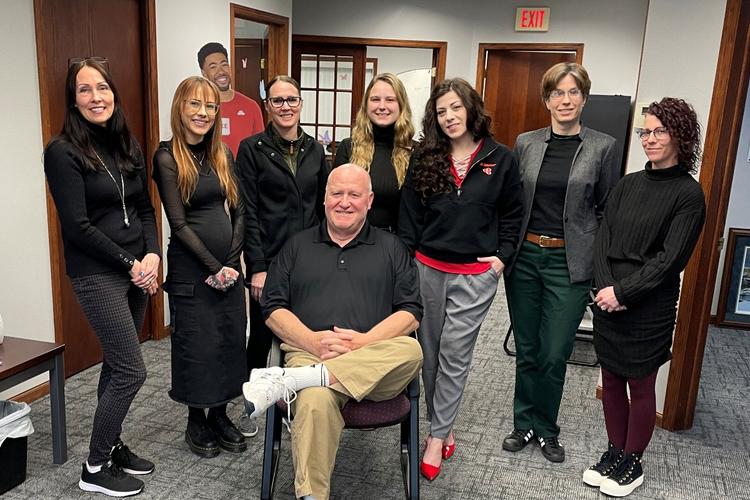
Our team brings 150+ combined years of experience to every conversation. Every call is answered live by a real team member — no automated menus. Whether you need help with a coverage question, a policy change, or guidance after an unexpected event, we are here and ready to help.
Our Coverage
We help Central Minnesota families and businesses with:
🚗 Auto Insurance
🏠 Home and Renters Insurance
🌂 Life Insurance
💼 Business Insurance
🏍️ Motorcycles, Snowmobiles, and Watercraft
☂️ Umbrella Liability and Personal Articles
Serving Near and Far
While we are proudly rooted in Central Minnesota — serving Sauk Rapids, Sartell, St. Cloud, Foley, and surrounding communities in Stearns, Benton, Morrison, and Sherburne counties — our team is also licensed in Wisconsin and South Dakota, and Paul is personally licensed in Minnesota, Wisconsin, South Dakota, North Dakota, and Nevada. Wherever life takes you, we can help.
Frequently Asked Questions
If I hit a deer near Sauk Rapids, does my auto policy cover the damage? Damage from striking a deer is generally handled under comprehensive coverage, subject to the policy terms and deductible. Move to a safe location, contact law enforcement when appropriate, and do not approach an injured animal.
What if I swerve to miss a deer and hit a ditch or guardrail instead? When there is no contact with the animal, damage from hitting a ditch, guardrail, tree, or another vehicle is generally handled under collision coverage. The deductible and other policy terms still apply.
If I slide on frost or black ice and hit something, what coverage applies? Collision coverage generally addresses damage to your own vehicle after a skid into another vehicle or object, while liability coverage may address damage you cause to others. Your selected coverages, limits, and deductibles determine what may apply.
Does my auto policy cover a windshield crack after a cold October night? Comprehensive coverage may address glass damage. Minnesota drivers with comprehensive coverage may select an option for safety-glass repair or replacement without a deductible, but whether you selected that option depends on your policy.
Should I review my auto coverage before driving around harvest equipment on roads in Benton and Stearns counties? It can be useful to confirm your liability, collision, comprehensive, and deductible selections before fall travel. Coverage depends on what happens, while extra following distance and careful passing remain important around slow-moving machinery.
Does home coverage help with accidental fire or smoke damage from a furnace, fireplace, or space heater? Accidental fire and smoke damage may be covered, subject to policy terms and exclusions. Maintenance, wear, and unsafe use are separate issues, so review your policy and follow local fire-safety guidance.
Are frozen or burst pipes covered if my home loses heat? Resulting water damage may be covered when reasonable steps were taken to maintain heat and prevent freezing. Coverage can differ when a home is vacant, heat was not maintained, or other exclusions apply.
Is sewer or sump-pump backup the same as flood coverage? No. Water entering through a sewer, drain, or sump pump is generally handled separately and may require an added endorsement, while surface flooding usually requires separate flood coverage. One does not automatically replace the other.
Does my home policy cover water damage from an ice dam? Water damage caused by an ice dam may be covered, but the cost to remove the ice dam or correct maintenance issues may not be. The cause of the damage, deductible, and policy terms determine what may apply.
Could my home policy help if a trick-or-treater is hurt on my property? Personal liability or medical payments coverage may help, depending on what happened and the policy terms. Keep steps and walkways lit and clear of leaves, cords, and decorations to reduce fall hazards.
Does my landlord’s policy cover my belongings in a Sauk Rapids, Sartell, or St. Cloud apartment? A landlord’s policy generally protects the building, not a tenant’s furniture, electronics, clothing, or other personal property. Renters coverage may also include personal liability and additional living expenses for a covered loss.
Can renters coverage help if items are stolen from my car at a fall event? Personal property coverage may apply to covered belongings stolen from a vehicle, subject to limits and the deductible. Damage to the vehicle itself is handled under auto coverage rather than renters coverage.
Can renters coverage help if smoke or a burst pipe makes my apartment unlivable? For a covered loss, personal property coverage may address damaged belongings, and additional living expense coverage may help with necessary costs above normal living expenses while the rental is uninhabitable. Limits and policy terms apply.
Is the coverage I get through work enough for the people who depend on me? Workplace coverage can be a useful starting point, but limits and portability vary. Compare it with your household’s income needs, debts, housing costs, and long-term goals before deciding whether an individual policy deserves consideration.
When should I review my beneficiary and family protection coverage? Review after marriage, divorce, a birth or adoption, a home purchase, a job change, or a major income change, and periodically even when nothing significant has changed. Beneficiary choices and coverage amounts should still reflect your current wishes and household needs.